ESG data assurance: an introduction for credible reporting
Last updated 30th October 2026
ESG data is increasingly used alongside financial information to inform investment, lending, procurement, risk management and strategic decisions. ESG data assurance provides an independent assessment of whether selected sustainability information has been prepared against suitable criteria and is supported by appropriate evidence. Done well, it improves confidence in reported information, identifies weaknesses in data and controls, and helps organisations make disclosures that can withstand stakeholder scrutiny.
This introductory guide explains ESG data assurance, how it relates to financial reporting, and what limited and reasonable assurance mean. If you are already preparing for an assurance engagement, read our practical guide: Assurance readiness: the key to having confidence in your ESG reporting.
Why ESG data assurance matters
Sustainability reporting has moved closer to the centre of corporate reporting. In its 2026 State of Play report (1), based on 2024 information from large companies across major jurisdictions, the International Federation of Accountants reported that 97% disclosed sustainability-related information, 75% obtained assurance over at least some sustainability disclosures, and 77% included sustainability information in annual or integrated reports.
Those figures show both how widespread sustainability reporting has become and the continuing gap between disclosure and assurance. Publishing a metric does not, by itself, demonstrate that the underlying data is complete, accurate or consistently prepared. Independent assurance can provide users with greater confidence in the information, while giving management a clearer view of weaknesses in methods, evidence, ownership and internal controls.
Regulation is increasing the focus on assurance. Requirements vary by jurisdiction, company size, reporting period and the information being disclosed. The EU Corporate Sustainability Reporting Directive introduced assurance over sustainability reporting for companies within scope, initially at a limited-assurance level. Other regimes and market frameworks also include assurance, verification or third-party review requirements or incentives. Because this landscape continues to change, organisations should confirm their current obligations rather than relying on a static list of regulations. Voluntary frameworks such as the SBTi Corporate Net-Zero standard V2 are raising assurance expectations around target setting and climate transition planning.
What is ESG data assurance?
ESG data assurance is an independent engagement in which an assurance practitioner evaluates selected environmental, social or governance information against defined criteria. The scope might include greenhouse gas emissions, energy, water, waste, workforce or other sustainability disclosures. It can also include qualitative information, provided there are suitable criteria against which that information can be assessed.
An assurance engagement normally considers the reported information and the processes that produced it. Depending on the scope and level of assurance, this may involve understanding the reporting boundary and methodology, assessing risks of material misstatement, reviewing data collection and internal controls, testing samples, tracing figures to supporting evidence, challenging estimates and evaluating the final disclosure.
The result is usually a formal assurance statement that describes the subject matter, reporting criteria, scope, level of assurance, work performed and conclusion. Assurance is different from consulting or pre-assurance: an independent assurer must preserve the objectivity required to reach and report a conclusion.
How ESG data assurance relates to financial reporting
The connection is increasingly practical. Sustainability-related risks and opportunities can affect revenue, operating costs, asset values, access to finance, insurance, investment decisions and business resilience. ESG information may therefore sit in an annual or integrated report, support narrative reporting, or inform assumptions and judgements used elsewhere in corporate reporting.
However, assurance over ESG information is not the same engagement as an audit of financial statements. Financial statement audits are conducted under financial-audit standards and provide reasonable assurance on the financial statements as a whole. Sustainability assurance has its own scope, criteria and conclusion, and may be limited or reasonable. The level required depends on the applicable law, framework and engagement terms.
Where the same information is presented in both the financial statements and the sustainability report, the sustainability assurance practitioner is expected to evaluate whether any material inconsistency exists and address such matters before issuing the assurance conclusion.
This distinction matters because users may otherwise assume that every ESG figure in an annual report has been tested to the same depth as the audited financial statements. Clear scoping and labelling help readers understand which information has been assured, under which standard, and to what level.
How assurance supports data quality, business risk and stakeholder confidence
· Data quality: assurance testing can identify inconsistent definitions, missing evidence, calculation errors, unsupported assumptions, weak audit trails and gaps in reporting boundaries.
· Business risk: unreliable ESG information can lead to poor decisions, compliance failures, inefficient investment, reputational damage and increased scrutiny from investors, lenders, customers or regulators.
· Governance and controls: preparing for assurance encourages clearer ownership, documented methodologies, review controls, version control and evidence retention.
· Stakeholder confidence: an independent conclusion helps users judge whether specified information is reliable enough for its intended purpose. It does not remove uncertainty or guarantee future performance, but it can make the basis of confidence much clearer.
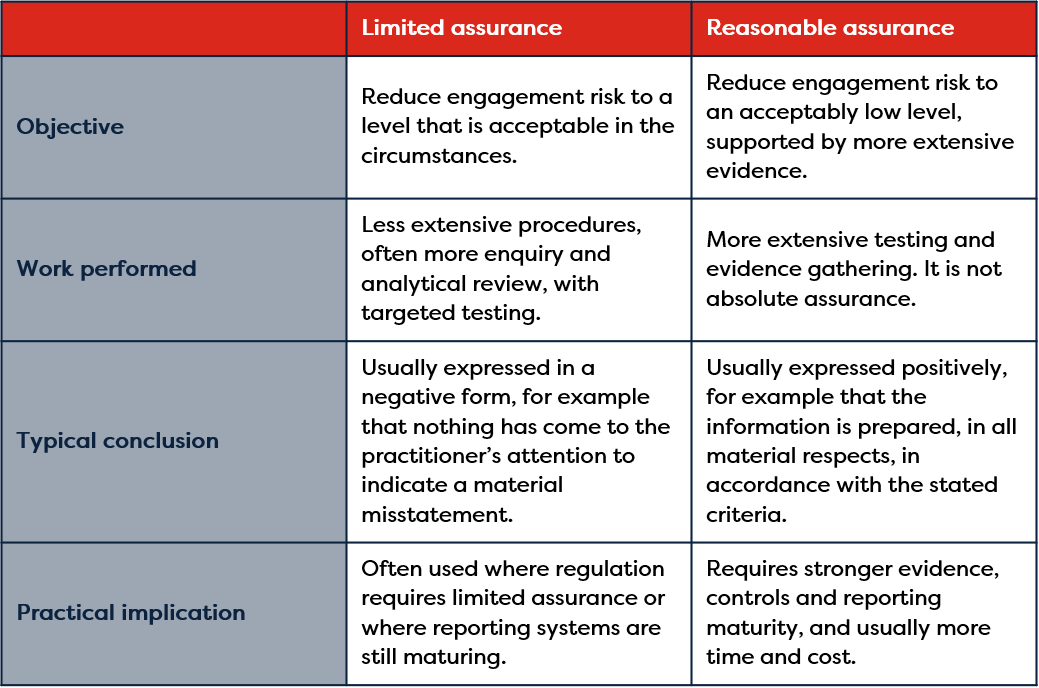
Limited and reasonable assurance: what is the difference?
Both levels require planning, evidence gathering and professional judgement, but they differ in the extent of work and the form of conclusion.
Which standards and frameworks are relevant?
The assurance standard governs how the assurance engagement is performed. The reporting framework or other criteria governs how the sustainability information is prepared. These are related, but they are not interchangeable.
· ISAE 3000 (Revised) is an established international standard for assurance engagements other than audits or reviews of historical financial information. ISAE 3000 will be replaced by ISSA 5000 for sustainability assurance engagements after 15 December 2026.
· AA1000 Assurance Standard (AA1000AS) is designed for sustainability assurance and includes attention to adherence to the AccountAbility Principles.
· ISSA 5000, General Requirements for Sustainability Assurance Engagements, provides a global baseline for sustainability assurance engagements. It is effective from 15 December 2026, with early adoption encouraged.
· ISO 14064-3 provides requirements and guidance for verification and validation of greenhouse gas statements.
The information being assured may have been prepared under criteria from, for example, the GRI Standards, IFRS Sustainability Disclosure Standards, European Sustainability Reporting Standards, GHG Protocol, CDP or GRESB. The appropriate combination depends on what is being reported, the intended users and any legal or contractual requirement.
What should an organisation expect from assurance?
The precise process depends on scope, criteria and level of assurance, but organisations should be ready to explain how information moves from source to disclosure. That normally means clear data owners, documented boundaries and methodologies, retained source evidence, review and approval controls, consistent calculations, and an audit trail for changes.
Assurance does not create good data. It tests and reports on information and controls within the agreed scope. If methods, evidence or governance are weak, an assurance engagement may identify misstatements, control weaknesses or limitations that require remediation. Addressing these issues early can reduce avoidable rework and make future reporting cycles more efficient.
Assurance, verification and assurance readiness
The terms are sometimes used loosely, so it is important to define the service being provided. Assurance is an independent engagement that results in a formal conclusion. It focuses on the usefulness in decision-making. Verification is often used for the evaluation of a specific statement or dataset, particularly greenhouse gas information, and may be conducted under standards such as ISO 14064-3. Assurance readiness, also called pre-assurance, is a preparatory review designed to identify gaps before formal assurance. It is advisory rather than the independent assurance conclusion itself.
Simply speaking, Assurance is to answer the question “Can stakeholders rely on this GHG information for decision making?” verification is asking “Is the reported data correct according to the reporting criteria?”.. And Assurance readiness is to address “Is the information ready to withstand independent assurance?”.
For a practical explanation of preparing data, methodologies, controls and evidence, read Assurance readiness: the key to having confidence in your ESG reporting. For a broader introduction to common assurance questions, watch our ESG assurance webinar.
Build confidence in your ESG reporting
Reliable ESG information supports better decisions as well as stronger disclosure. BIP.Verco combines sustainability subject-matter expertise with assurance and data capability to help organisations understand the right scope, strengthen reporting systems and obtain independent assurance or verification over agreed information.
Discuss your ESG assurance requirements with BIP.Verco.
Whether you need formal assurance, greenhouse gas verification or an assurance-readiness review, talk to our team about the reporting criteria, level of assurance and evidence your organisation needs.
The importance of sustainability expertise in sustainability reporting and assurance
Find out about our assurance services